Chinese economy enjoys a healthy energy supply buffer
China's oil inventory cushion and refined product export ban insulate the domestic market from the Hormuz closure. However, China's core growth model remains imbalanced.
Summary
- Healthy Energy Supply: Ahead of the Iran conflict, China was better positioned than most major energy importers. Onshore oil inventories stood at roughly 1.2bn barrels, providing 113 days of seaborne import cover, rising to 250 days when measured against domestic transportation fuels alone.
- Export Ban: A ban on refined product exports enacted on March 12 further insulates the domestic market, but at the cost of widening supply shortages across the broader Asia-Pacific region. Seaborne clean product exports have collapsed from 640 kbd to just 90 kbd since the bank took effect. Refinery output will fall more than 1 Mbd y/y in April, albeit domestic fuel demand will remain largely stable.
- The 4.5% Growth Target: We expect China to grow at 4.5% this year, at the low end of the growth target range. The mode of growth continues to exacerbate longstanding imbalances. The government leaned heavily on infrastructure investment in Q1, with expenditures up 8.9% y/y, while manufacturing investment also recovered to 4.1% y/y. We have revised headline inflation up 40bp to 1.2% on Iran energy price concerns, though weak underlying consumption limits broader price pressures.
- Consumer Disappointment: our calculation of Chinese inflation-adjusted retail sales growth managed just 1.4% y/y in Q1, well below industrial production growth of 6%, the latter of which reaccelerated from Q4 2025. Until household demand begins to show signs of outpacing production expansion, China’s structural reliance on external demand and investment to drive growth will persist.
Market Analysis
China has plenty of headroom to absorb a longer-run energy supply shock, but it comes at expense of the rest of East Asia.
Over the past six weeks, our regular cadence of country and region level economic updates has been disrupted by the Iran war. As the threat of an extended Strait of Hormuz closure reshapes the outlook for global growth and inflation, much of our focus has centered on scenario analysis given the unknowns around the conflict between the United States and Tehran. It is our view that the duration in which the Strait of Hormuz remains closed is the ultimate determinant of how bad things get across the global economy. In this week’s macro update, we check in on the state of the Chinese economy and provide our forecasted outlook for growth and inflation as the war in Iran continues.
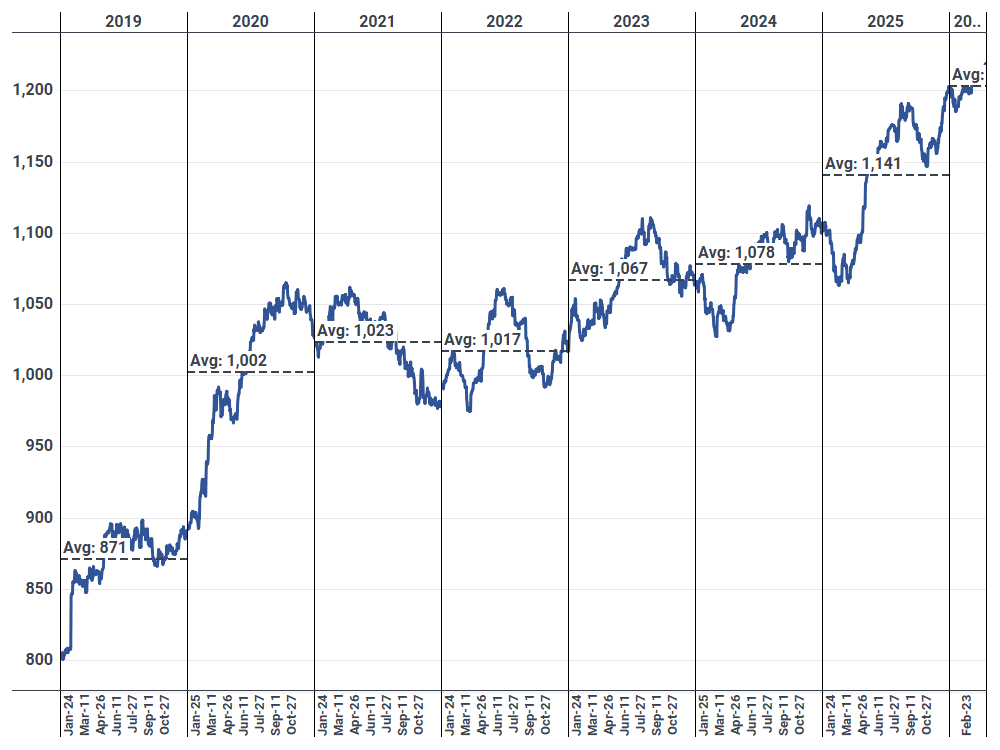
Domestic Chinese Onshore Oil Inventories (Mb)
Source: Kpler
Coming into the Iran conflict, China was better off than most other major energy importing nations. Chinese onshore oil inventories on February 28 were roughly 1.2bn barrels, equating to 113 days of seaborne oil import cover. Our days cover calculation rises to an impressive 250 days when accounting solely for Chinese domestic transportation fuels demand (~9.3 Mbd). Of the major East-Asian economies, only Japan is in a similarly advantageous supply position.
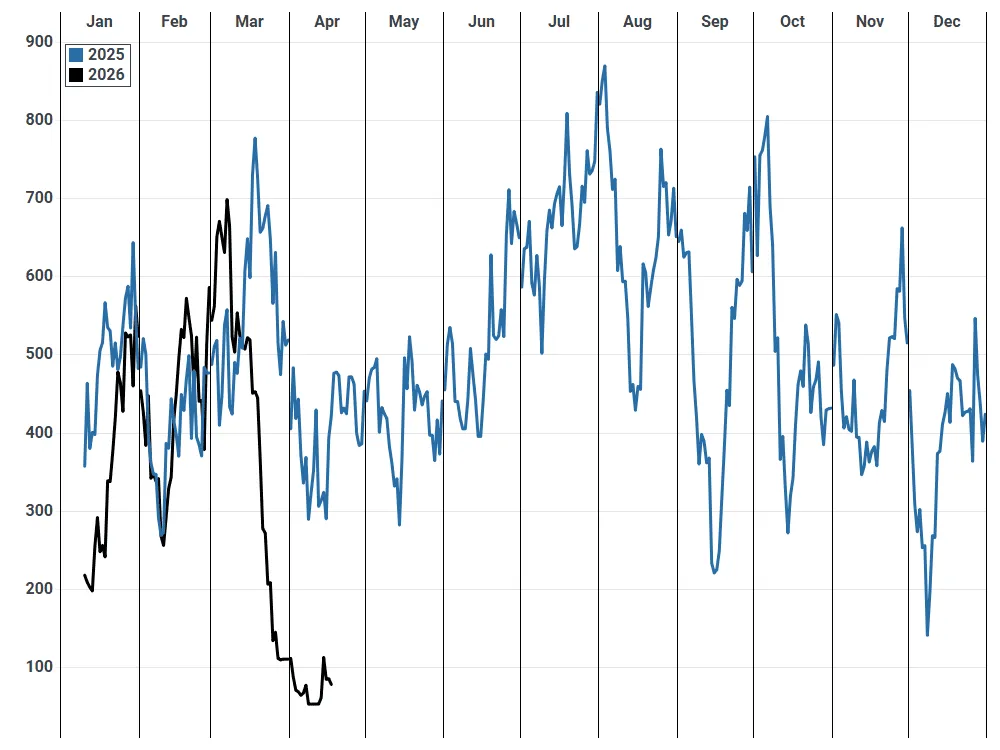
On March 12, a bit over a week after the US began combat operations in Iran, the Chinese government took action to restrict refined product exports. This was a major move. In 2025, combined gasoil/diesel, gasoline, and jet exports leaving China finished at 640 kbd. The move to restrict exports was unsurprising – the Chinese government tends to emphasize energy supply security when making policy decisions. On a 15-day moving average, Chinese seaborne exports of gasoline/naphtha, gasoil/diesel, and jet/kero have fallen to just 90 kbd, down from 640 kbd in the days before the export ban. The Chinese government has only allowed a few shipments to Australia, the Philippines, Singapore, Malaysia, and Japan, among a few others since the ban went into effect.
Daily Chinese Seaborne Core Clean Product Exports (kbd, 10-day ma)
Source: Kpler; volumes exclude shipments to Hong Kong
The export ban is having a big impact on domestic refinery runs, an unsurprising outcome as China’s refinery capacity far outpaces consumption. We currently expect Chinese throughput to finish at just 14.17 Mbd in April, down from 15.7 Mbd in February, and lower 1.1 Mbd against year earlier levels. However, domestic demand is only expected to decline slightly for reasons unrelated to the Iran war. This dichotomy effectively limits adverse supply and price impacts within China, while widening supply shortages throughout the broader Asia-Pacific region.

See why the most successful traders and shipping experts use Kpler