Middle East refining under pressure: damage, export disruption, and a two-speed recovery
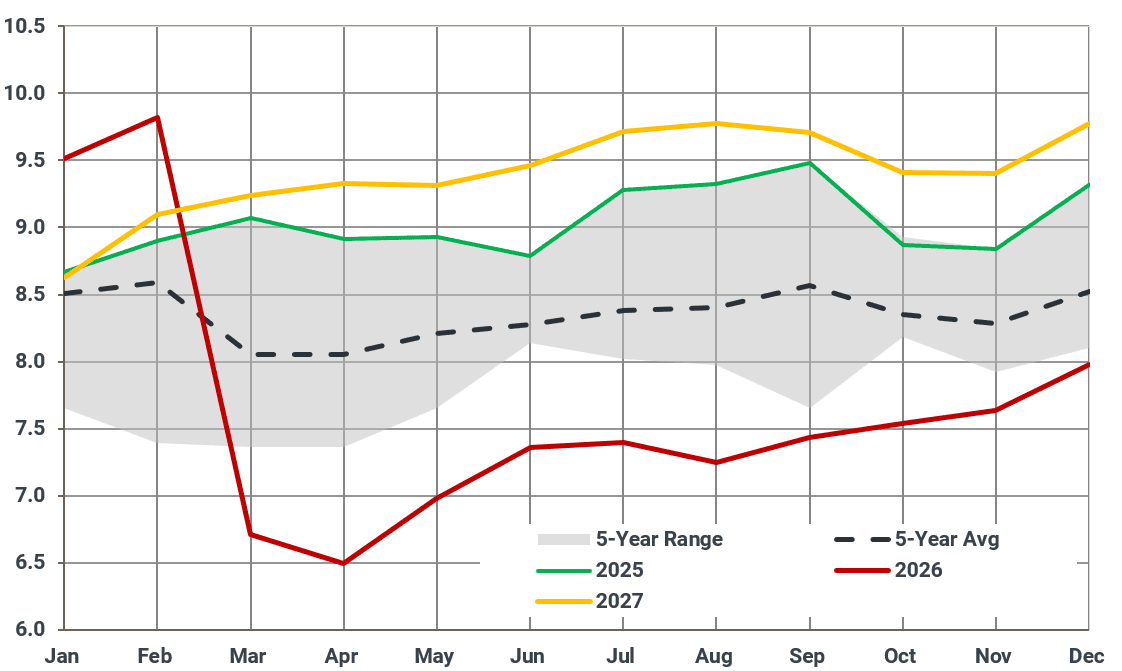
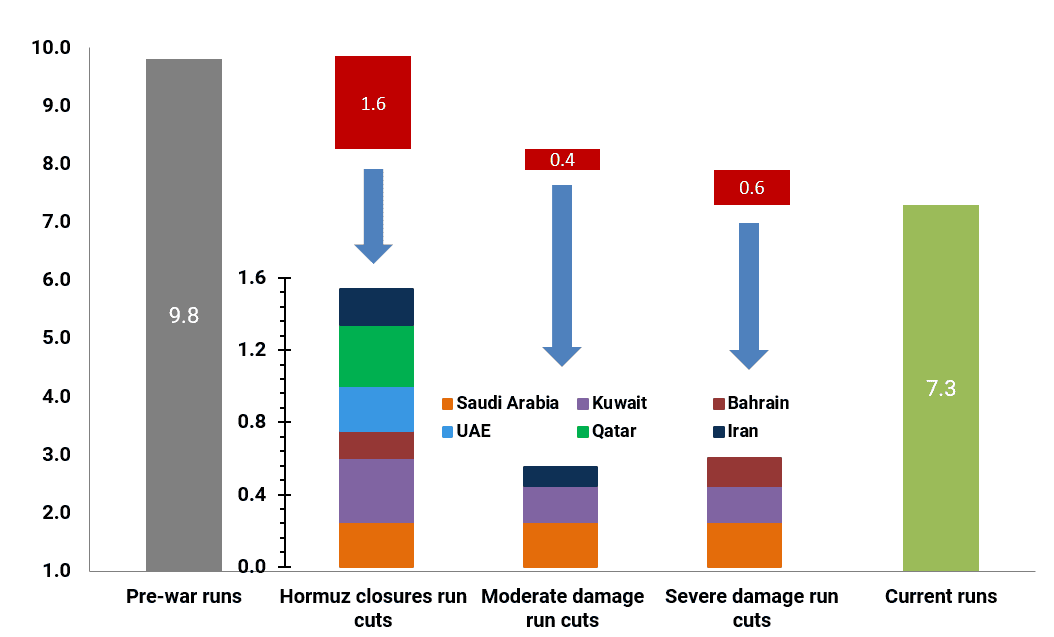
Middle Eastern refinery runs remain sizeably below pre-war levels at around 7.3 mbd versus 9.9 mbd in February 2026, reflecting a combination of physical refinery damage and constrained product evacuation through the Strait of Hormuz (SoH). Looking ahead, we expect a gradual recovery from Q4 2026, but a return to pre-war throughput remains unlikely before Q2 2027.
Near-term recovery is a logistics story; full normalisation is a capacity restoration story.
Middle Eastern refinery runs began to recover in May, but renewed regional tensions and the effective closure of the Strait of Hormuz (SoH), followed by disruptions around Bab el-Mandeb (BeM), have interrupted the recovery since. Importantly, run losses have been substantially larger than the amount of refining capacity directly taken offline, as otherwise operational refineries have also curtailed throughput to manage rising product inventories amid restricted export flows.
Middle East refinery runs (mbd)
Source: Kpler
Our base case assumes prolonged disruption with transit remaining constrained through the rest of 2026 before a gradual reopening begins only in late Q4. Regional refinery runs have so far evolved broadly in line with our prolonged-conflict scenario. An improvement in Hormuz transit could therefore unlock a relatively quick initial rebound as operational refineries raise throughput and product evacuation normalises.
Beyond the initial rebound, damaged capacity will become the main constraint. Restoring heavily affected sites requires work across processing units, power, utilities and supporting infrastructure, while certain process equipment will require lengthy repairs or replacement. We therefore expect Q4 recovery to be primarily logistics-led, with the return of damaged capacity shaping the recovery thereafter and keeping a full return to pre-war throughput constrained until Q2 2027.
Middle East refinery run losses by driver and country (mbd)
Source: Kpler & IIR Energy
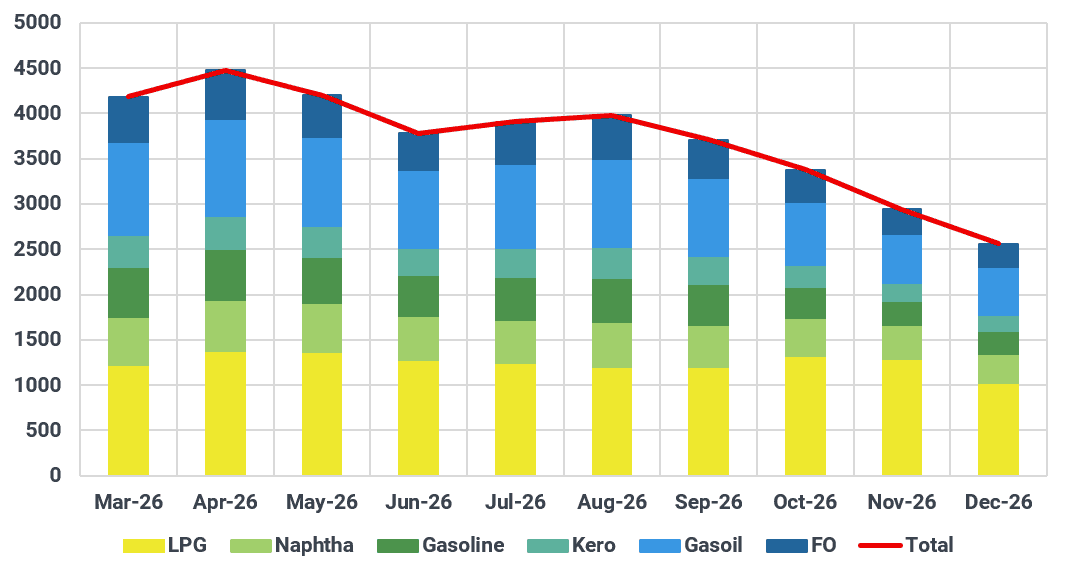
The Middle East has lost around 4 mbd of refined product supply since the start of the conflict.
The impact extends beyond refinery throughput alone. Between March and August, the Middle East has lost around 4 mbd of refined product supply relative to pre-conflict levels. Around 2.5 mbd of this reflects curtailed refinery output, while the remaining roughly 1.5 mbd comes from other regional supply streams, primarily LPG and NGL-derived naphtha.
Refined product loss, including supply from NGL, kbd
Source: Kpler
Refinery damage and export constraints leave recovery uneven across the Middle East.
The nature of the disruption differs significantly by country. Saudi Arabia, Kuwait and Bahrain combine substantial physical damage with some of the largest run losses, while the UAE and Iran remain more heavily constrained by product evacuation. Qatar faces a longer recovery following damage to Pearl GTL, while Oman stands apart, with its location outside Hormuz allowing runs to remain near capacity.

See why the most successful traders and shipping experts use Kpler