

US copper imports on course for record as stocks thin elsewhere
The United States imported a record volume of copper cathode on open-hatch vessels in July, well above the level required to balance domestic supply and demand. Meanwhile, the concentrate market remains extraordinarily tight, Chinese exchange stocks hold under a week of consumption, and a tighter sulphuric acid market threatens hydrometallurgical output in the DRC. With the prospect of a tariff on refined copper still unresolved, the stateside stockpile is unlikely to return to the wider market.
Record imports
The United States imported over 185kt of copper cathodes on open-hatch vessels in July, a record in Kpler’s trades. Open-hatch is the dominant route for cathode, but not the only one: in a typical month, containers and other modalities add a further 30 to 50kt, putting total deliveries for July at 215–235kt. That would test the record of 221kt, set in July 2025 during the first round of tariff speculation.
US copper cathode imports
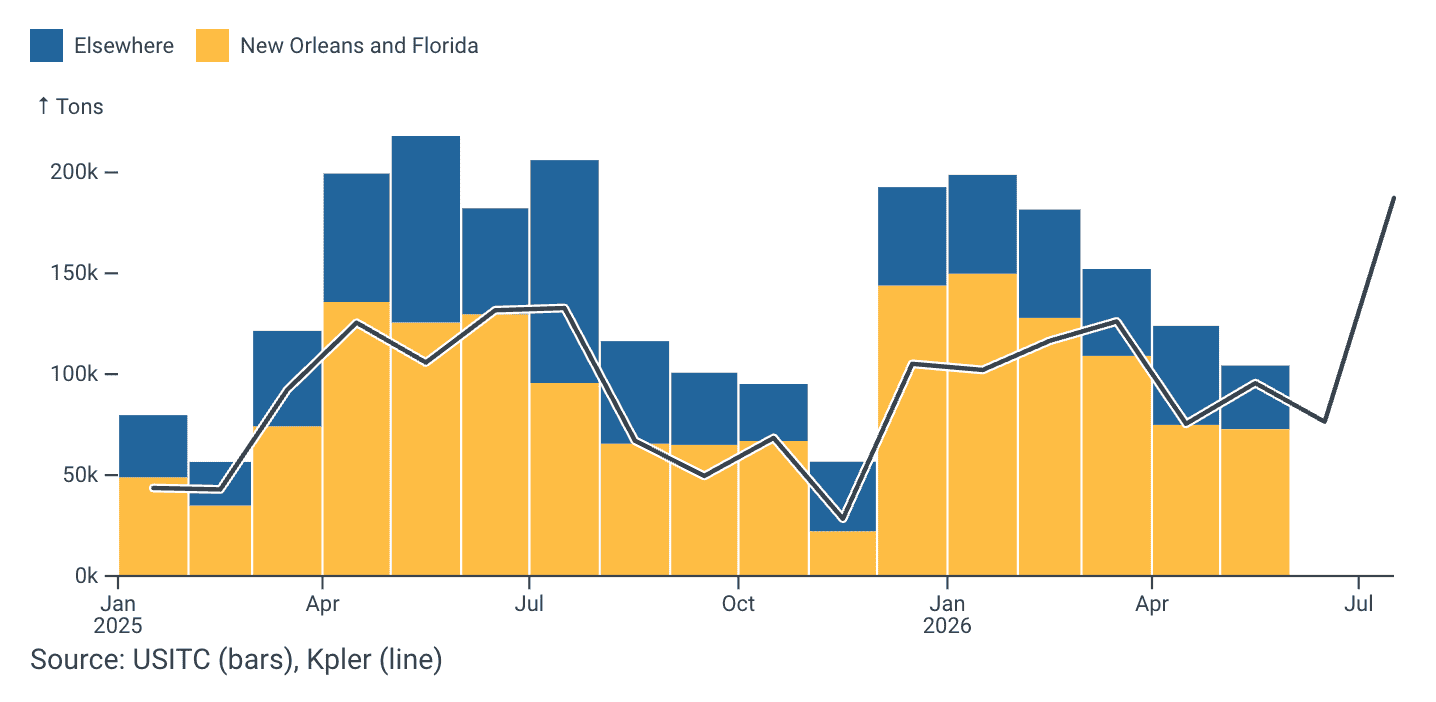
While the United States is dependent on copper imports, current flows clearly exceed the 70kt required on a monthly basis to balance domestic supply and demand. These flows reflect the continued arbitrage between CME and LME copper prices that first emerged with the possibility of a tariff on refined copper in February 2025.
Refined metal was exempted when tariffs on semi-finished and copper-intensive products took effect the following August, and the arbitrage narrowed accordingly. What remained was the option to phase in a duty on refined copper from January 2027. The deadline for a determination passed at the end of June without one, and that expectation is still priced into the forward curve, where the differential supports continued imports.
Limited cover outside the US
As copper stocks in the United States have reached unprecedented levels, those elsewhere have declined through Q2 and into Q3. SHFE stocks fell to a low of 69kt in the week ending 24 July before rebuilding to 110kt at month end, while LME ex-United States stood at 152kt at the same date. Both sit against more than 800kt of visible inventory in the United States.
Exchange registered copper inventories
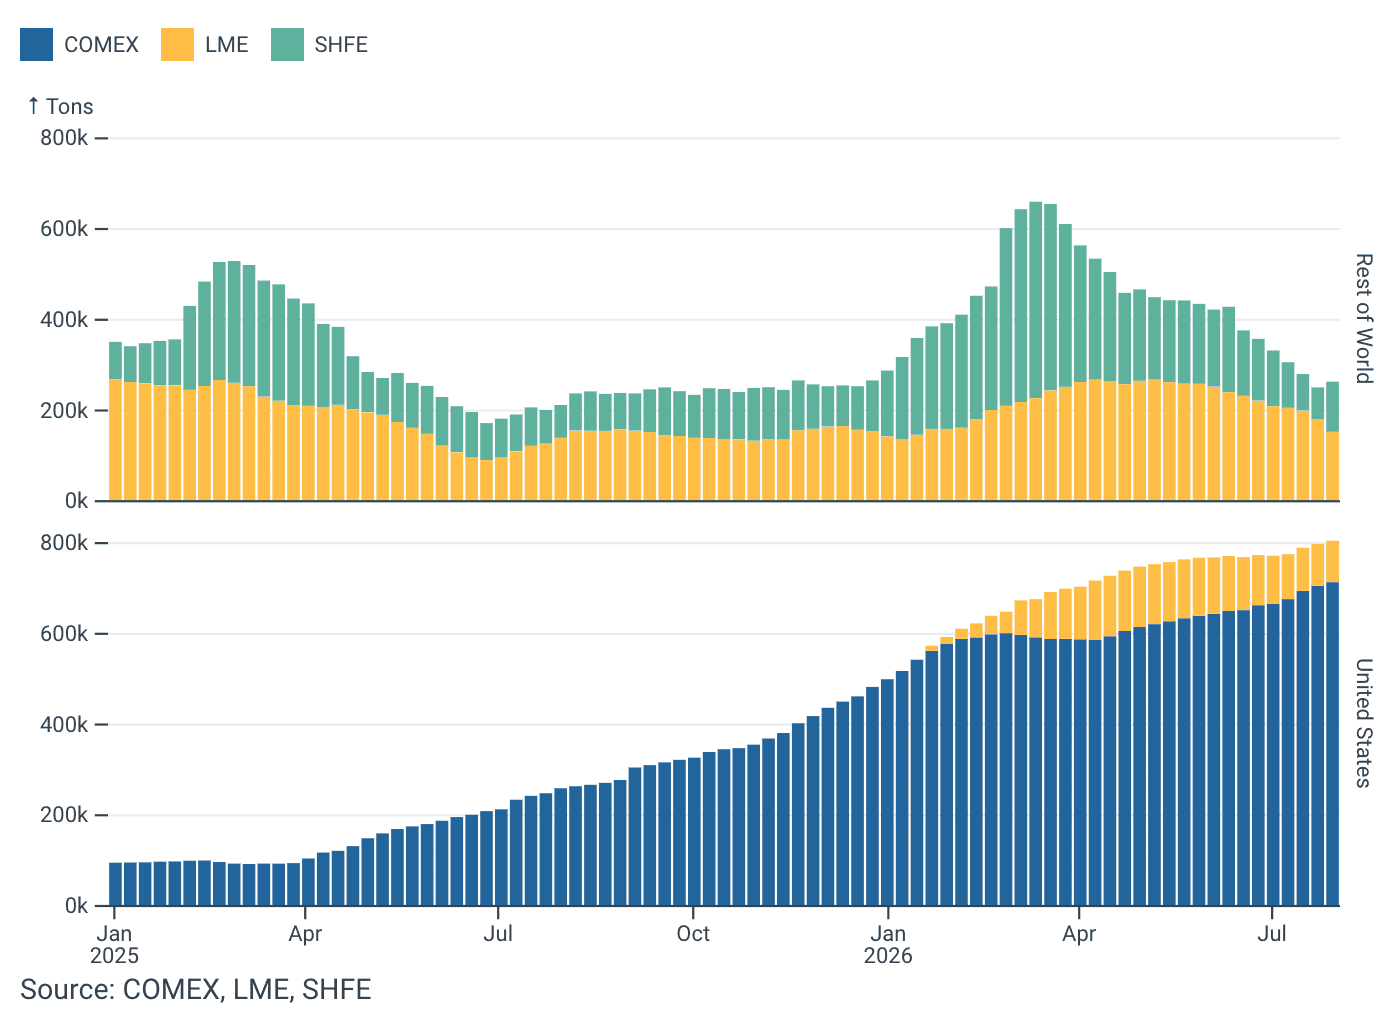
The US inventory covers close to five months of domestic consumption on USGS figures for 2025. China's SHFE, even after the rebuild, holds under a week of exchange-deliverable copper, and the recovery is only a week old. Bonded stock adds to the Chinese total, but only marginally. Availability has been further restricted by tighter VAT enforcement on scrap transactions, which has disrupted circulation and pushed end-users towards refined metal. The Yangshan import premium reached a 14-month high of $100/t in July, drawing in the imports behind the rebuild.
The Chinese demand pull competes directly with US imports. The DRC remains the largest supplier of seaborne cathode into China, but Congolese producers have redirected an increasing share to the US since the arbitrage emerged. Kpler’s trades for July recorded 57kt of cathode delivered from producers including Tenke Fungurume, Sicomines and Metalkol.

See why the most successful traders and shipping experts use Kpler






